If your Permanent Change of Station (PCS) orders point you to Redstone Arsenal, you have a strong tool for buying a home: the VA loan. The Department of Veterans Affairs (VA) backs these loans so qualified service members, veterans, and some surviving spouses can buy with little or no money down. Huntsville is growing fast, in part because of the move of U.S. Space Command (SPACECOM) headquarters to Redstone, and many newcomers are weighing whether to buy. This guide explains how your VA benefit works in Huntsville and Madison County in 2026.
At VeteranPCS, we read the official .gov and .mil sources so you do not have to guess. We are not your lender and we do not approve loans. We gather the public record into plain language and point you to the source for each number. For the full picture of the move, schools, and housing, start with our complete 2026 guide to PCSing to Redstone Arsenal.
The 2026 Madison County VA Loan Limit
You may have heard about a "VA loan limit." For Madison County, Alabama, the 2026 conforming and VA one-unit loan limit is $832,750. Madison County is a standard, non-high-cost county, so the baseline figure applies. That is up $26,250, or 3.26 percent, from the 2025 limit of $806,500, as announced when the FHFA set 2026 conforming loan limit values on November 25, 2025. The Federal Housing Finance Agency (FHFA) sets these figures each year. A higher ceiling of $1,249,125 exists in expensive housing markets, but it does not apply to Madison County.
Here is the part that surprises a lot of buyers. That $832,750 figure only matters if you have partial entitlement, which we explain in the next section. If you have full entitlement, there is no VA loan limit at all. You can review how this works on the VA's page about VA loan limits and entitlement.
Full vs. Partial Entitlement
Entitlement is the dollar amount the VA guarantees on your behalf. Lenders trust that guarantee, which is why VA loans often need no down payment. Understanding your own status is the single most useful thing you can do before you shop.
You have full entitlement if you have never used your VA loan benefit, or if you used it before and have since paid the loan off and sold the home. With full entitlement, the VA removed the old loan caps under the Blue Water Navy Vietnam Veterans Act of 2019. That means the $832,750 county limit does not cap you at all. Your loan size is set by what a lender approves based on your income and credit, not by the county figure.
You have partial entitlement if some of your benefit is still tied up. Common examples are an active VA loan you are still paying on, or a past VA loan that ended in a foreclosure or short sale. With partial entitlement, the county loan limit comes back into play, and you may need a down payment on the amount above your remaining entitlement. If you are not sure where you stand, our plain-language guide to how VA loan entitlement works walks through the math, and our overview of VA loan eligibility requirements helps you confirm you qualify in the first place.
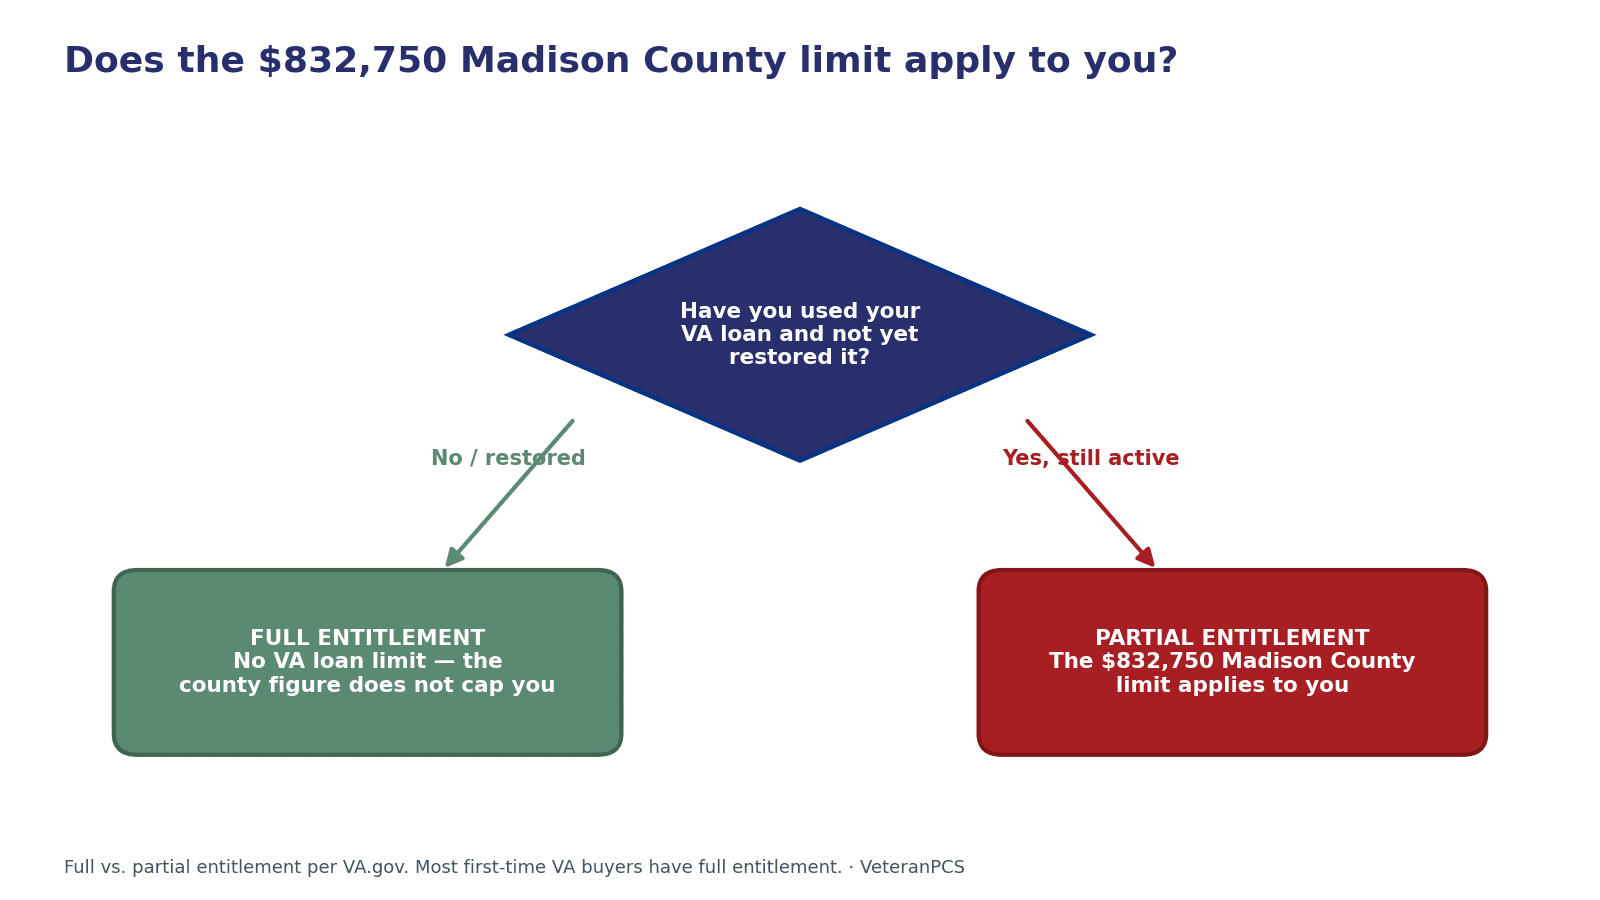
Whether the $832,750 Madison County limit applies depends on full versus partial entitlement.
The VA Funding Fee (and the Disabled-Veteran Waiver)
Most VA borrowers pay a one-time charge called the funding fee. It helps keep the program running for the next generation of buyers. The fee is 2.15 percent of the loan amount on a first use with no down payment, and 3.3 percent on a subsequent use. You do not have to pay it out of pocket, because the fee can be financed into the loan.
There is an important exception. The funding fee is waived for veterans who are rated 10 percent or more disabled by the VA. It is also waived for certain surviving spouses and for Purple Heart recipients on active duty. That waiver can save you thousands of dollars at closing. Confirm your own situation on the VA's page about the VA funding fee and closing costs. For a fuller look at why this benefit is so valuable, see our overview of the benefits of a VA loan.
Planning Your Next Move?
Connect with Veteran & Military Spouse Real Estate Agents and VA Loan Experts You Can Trust.
If you want help running real numbers for a Huntsville home, you can connect with a VeteranPCS agent who works with military buyers every day.
Alabama's Tax Breaks for Veterans
One of the quiet wins of buying in Huntsville is the tax picture. Alabama property taxes are already among the lowest in the nation, with a Madison County effective rate of roughly 0.40 to 0.52 percent. On top of that, the state offers real breaks for veterans.
Alabama exempts a disabled veteran's, or a qualifying surviving spouse's, principal residence from state property tax. The state also exempts military retirement pay from state income tax. Those two breaks can add up to meaningful monthly savings on a fixed budget. You can review how assessments and exemptions work on the Alabama property tax assessment page.
One budgeting note for every buyer, veteran or not. Always claim the homestead exemption on your principal residence, because a non-homestead tax bill runs roughly double. It is a simple step that protects your monthly payment.
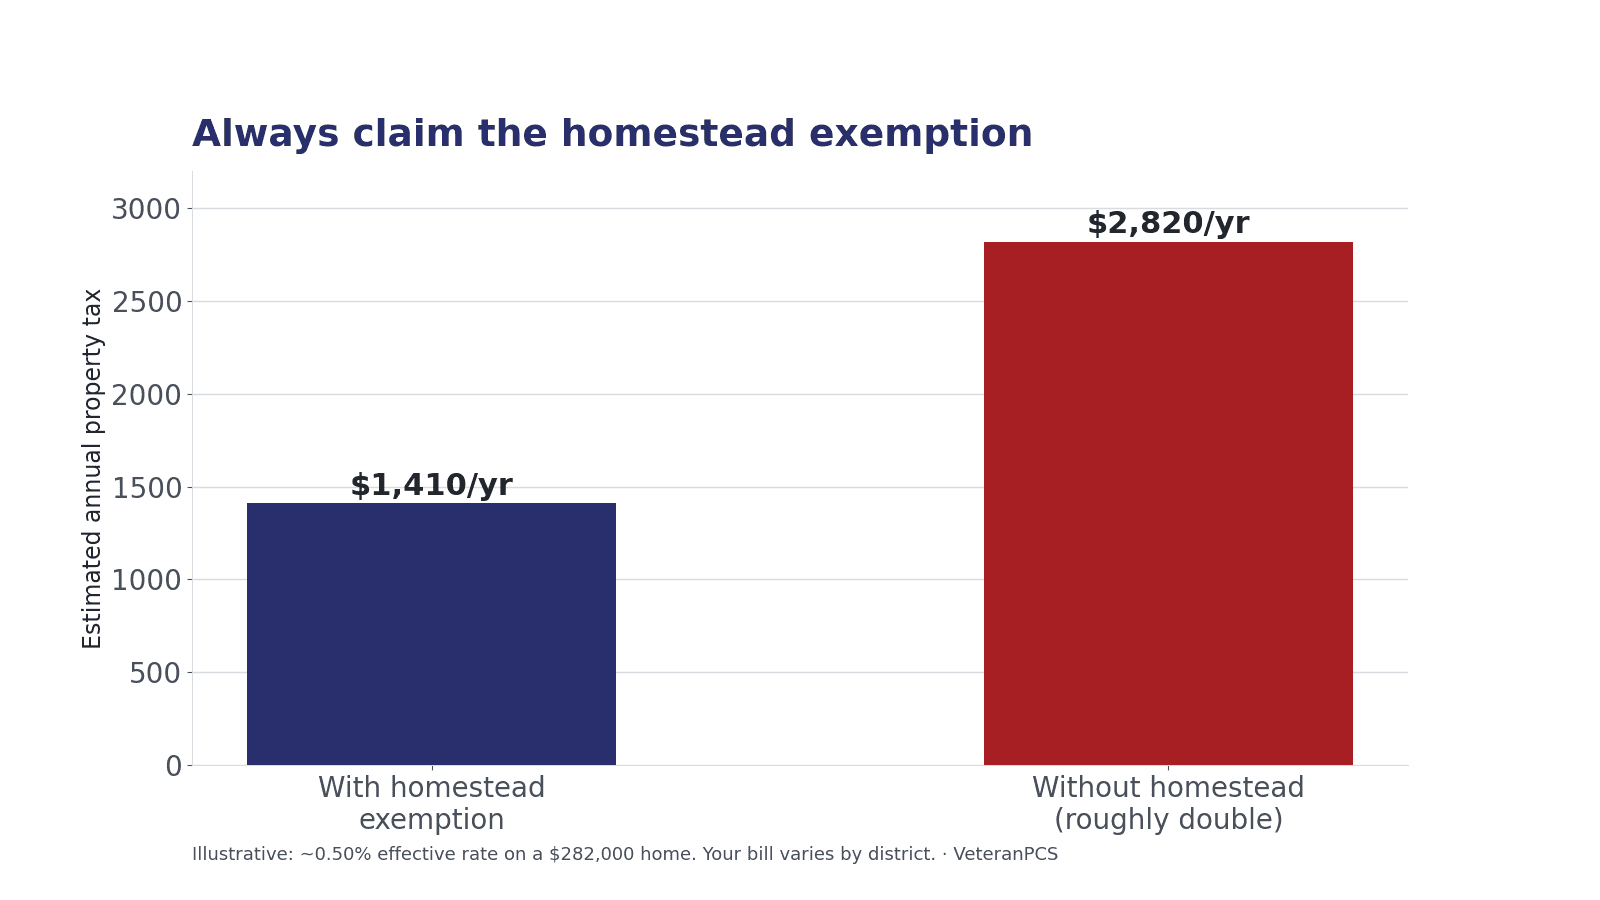
Claiming the homestead exemption roughly halves the bill. Figures are illustrative.
From Active Duty to a Civilian Redstone Job: Your Eligibility Still Counts
This is the part many Huntsville newcomers miss, and it matters. A lot of people moving for the SPACECOM headquarters are leaving active duty and stepping into civilian roles. They take jobs with the Department of Defense (DoD), NASA, the FBI, or one of the many defense contractors in the area. About 60 percent of the relocating SPACECOM headquarters staff are government civilians, as the Army noted when it unveiled the sign at the future Redstone home of Space Command.
Free First-Time Homebuyer Guide
Make your move less stressful with our step-by-step first-time homebuyer guide.
We respect your privacy. Unsubscribe anytime.Here is the good news. Your VA loan eligibility is earned through your qualifying military service, and it does not disappear when you separate. If you served long enough to earn the benefit, you keep it. So a veteran can use VA-loan eligibility from past service while earning brand-new civilian income at Redstone or in the offices of Cummings Research Park, one of the largest research parks in the country. Your new paycheck simply helps you qualify; it does not erase the benefit you already earned.
One more tool worth knowing about if you sell later: a VA loan can sometimes be passed to a qualified buyer. Our guide to VA loan assumptions explains when that helps and what to watch for.
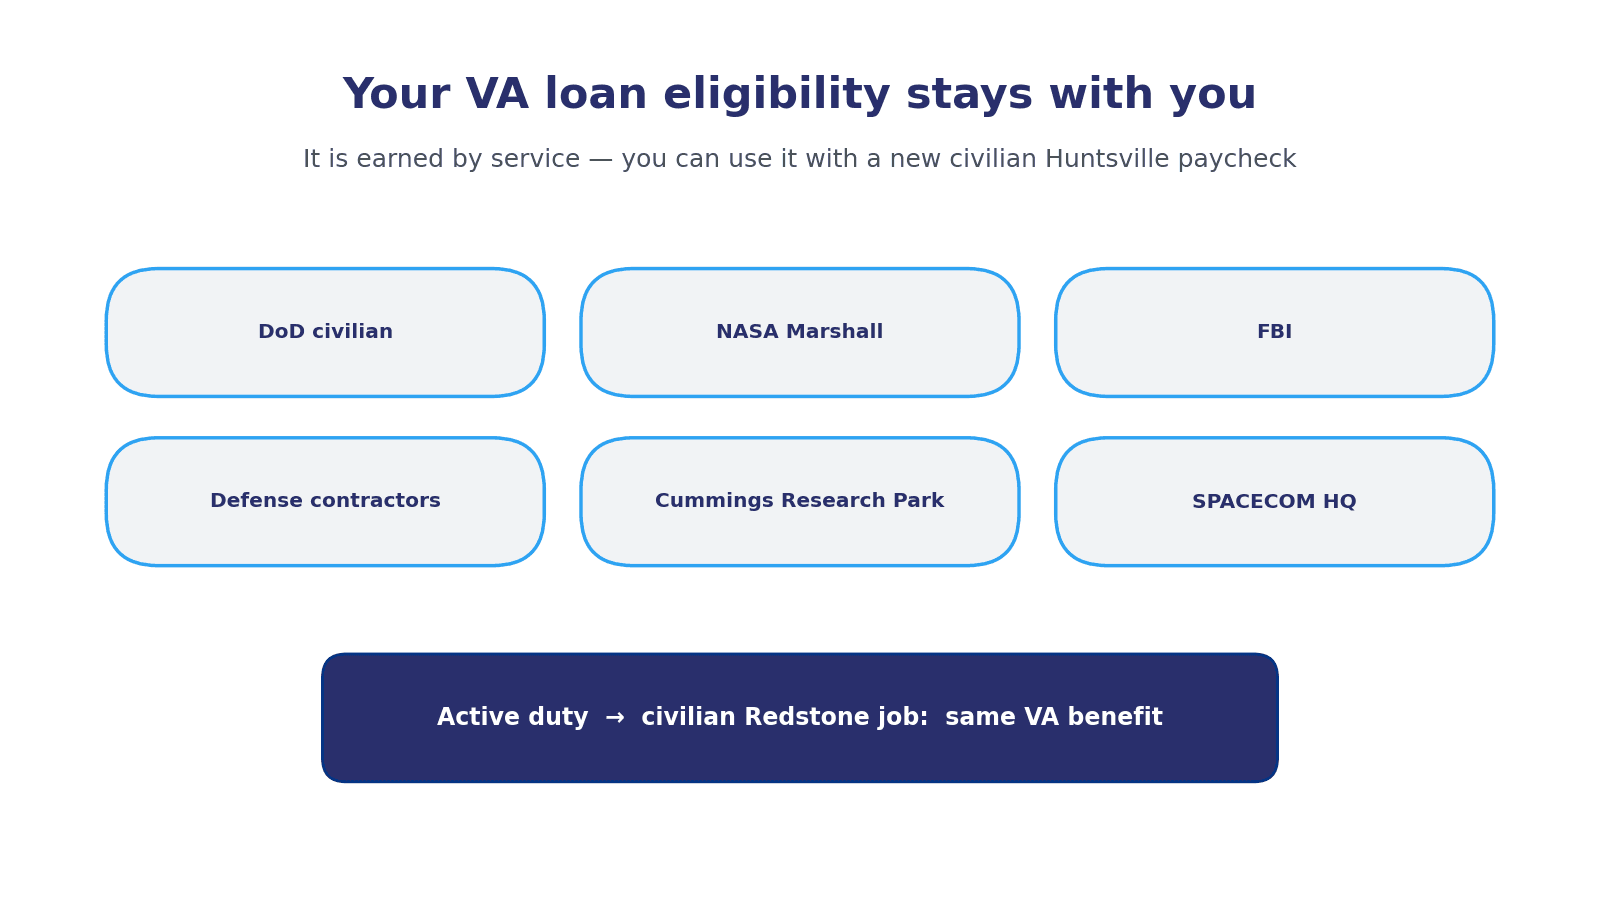
Your VA loan eligibility is earned by service and follows you into a civilian Redstone career.
Putting It All Together
A VA loan is one of the strongest ways to buy a home in Huntsville. Start by learning whether you have full or partial entitlement, since that decides whether the $832,750 Madison County limit even applies to you. Plan for the funding fee, but remember it is waived if you are rated 10 percent or more disabled. Lean on Alabama's low property taxes and veteran exemptions. And know that your eligibility follows you from the uniform into a civilian Redstone career.
When you are ready to turn this into a real home search, a military-experienced agent and lender can save you time and money.
If this guide helped you, please share it with anyone in your unit or military network who is headed to Huntsville.
This content is for informational purposes. Consult a professional for personal financial decisions.