A VA funding fee refund can put thousands of dollars back in your pocket. But it does not happen just because you got a disability rating after you bought your home. The rule turns on one date: the effective date of your VA disability award. This guide explains who qualifies, how VA sends the money, and what to do if you think you are owed a refund.
New to the fee itself? Start with our complete guide to the VA funding fee, then come back here.
What the VA Funding Fee Is
The VA funding fee is a one-time charge on most VA-backed home loans. It helps keep the VA loan program running for future borrowers. The amount depends on the type of loan, your down payment, and whether you have used a VA loan before.
Here are the purchase loan rates that have been in effect since April 7, 2023, per VA.gov's funding fee page:
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
The same page lists 0.5% for an IRRRL (Interest Rate Reduction Refinance Loan, the VA's streamline refinance) and 0.5% for a loan assumption.
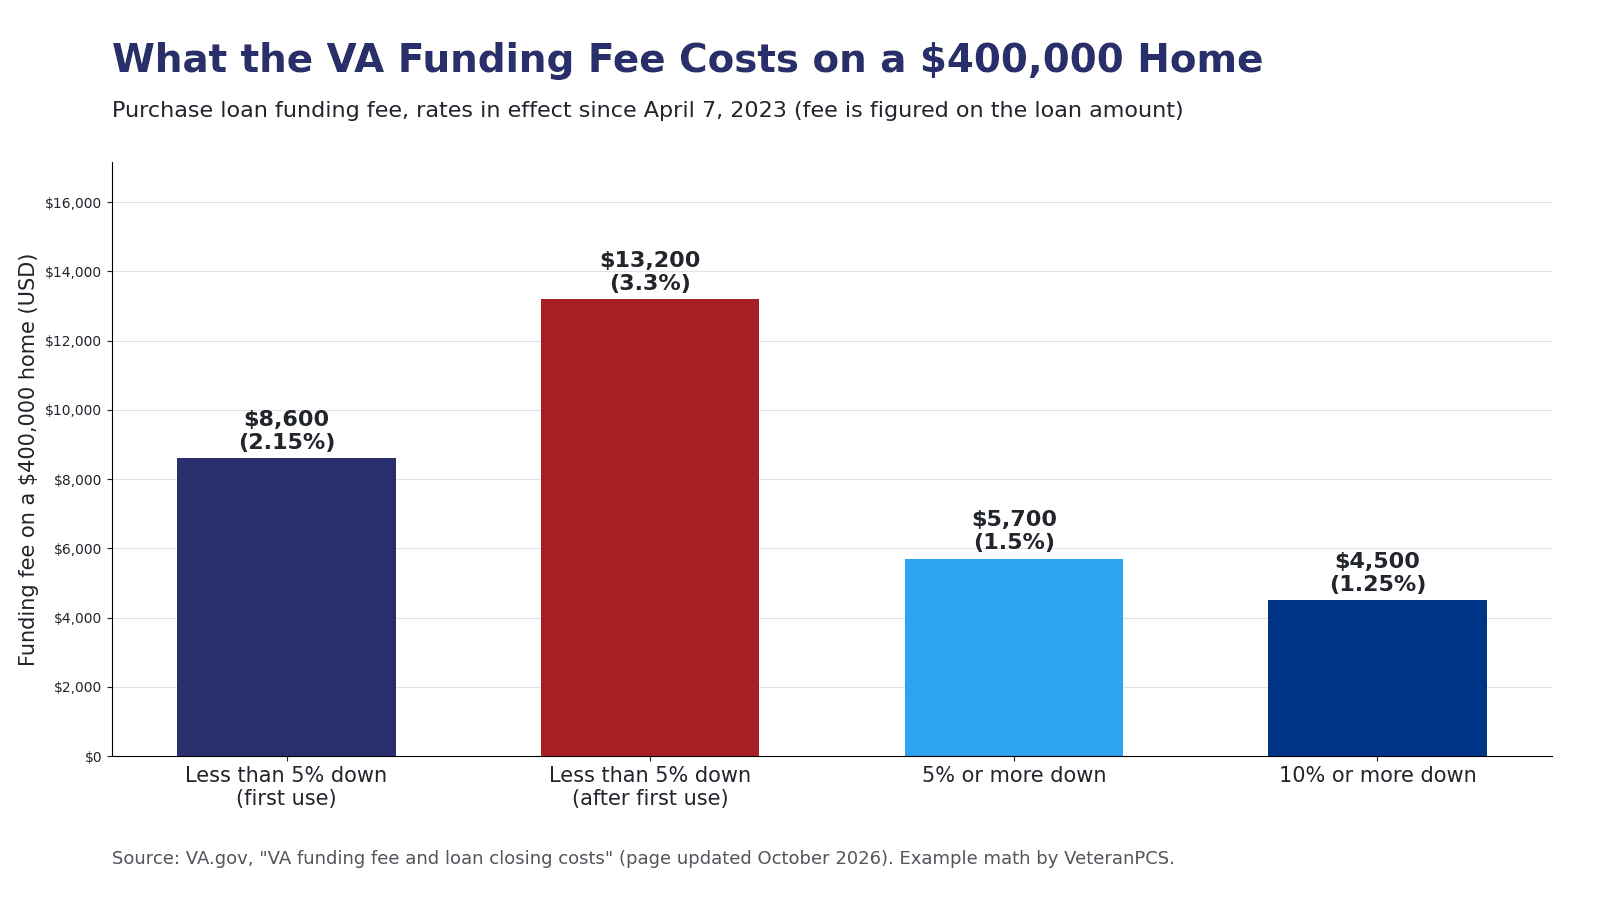 What the funding fee costs on a $400,000 home. The fee is figured on the loan amount, so a down payment lowers both the rate and the base. Source: VA.gov rates; example math by VeteranPCS.
On a $400,000 home with no money down, the first-use fee is $8,600. That is why a refund is worth checking on.
Who Does Not Pay the Fee at All
Some buyers are exempt from the start. Per VA.gov, you do not pay the funding fee if any of these is true:
- You receive VA compensation for a service-connected disability.
- You are eligible for that compensation but receive retirement or active-duty pay instead.
- You are a surviving spouse who receives Dependency and Indemnity Compensation (DIC).
- You are a service member with a proposed or memorandum rating, before closing, that says you are eligible for compensation based on a pre-discharge claim.
- You are on active duty and show proof of a Purple Heart on or before your closing date.
Your lender checks your exemption status when it pulls your Certificate of Eligibility (COE). Our guide to the VA loan certificate of eligibility explains how to get one and what to check on it.
When You Can Get a VA Funding Fee Refund
If you paid the fee and later get a disability award, you may qualify for a refund. The key test is simple: the effective date of your award must be before your loan closing date.
VA explained this in a November 2026 article, VA home loan funding fee refunds: Why timing matters. Here are the main points:
- A rating you get after closing does not, by itself, earn a refund.
- What counts is the effective date on your award, not the date VA decided your claim.
- The effective date is generally the later of two dates: the day VA received your claim, or the day you became entitled.
- VA's own example: if you close on June 15 and your effective date is June 1, you may qualify. If your effective date is July 1, you generally would not.
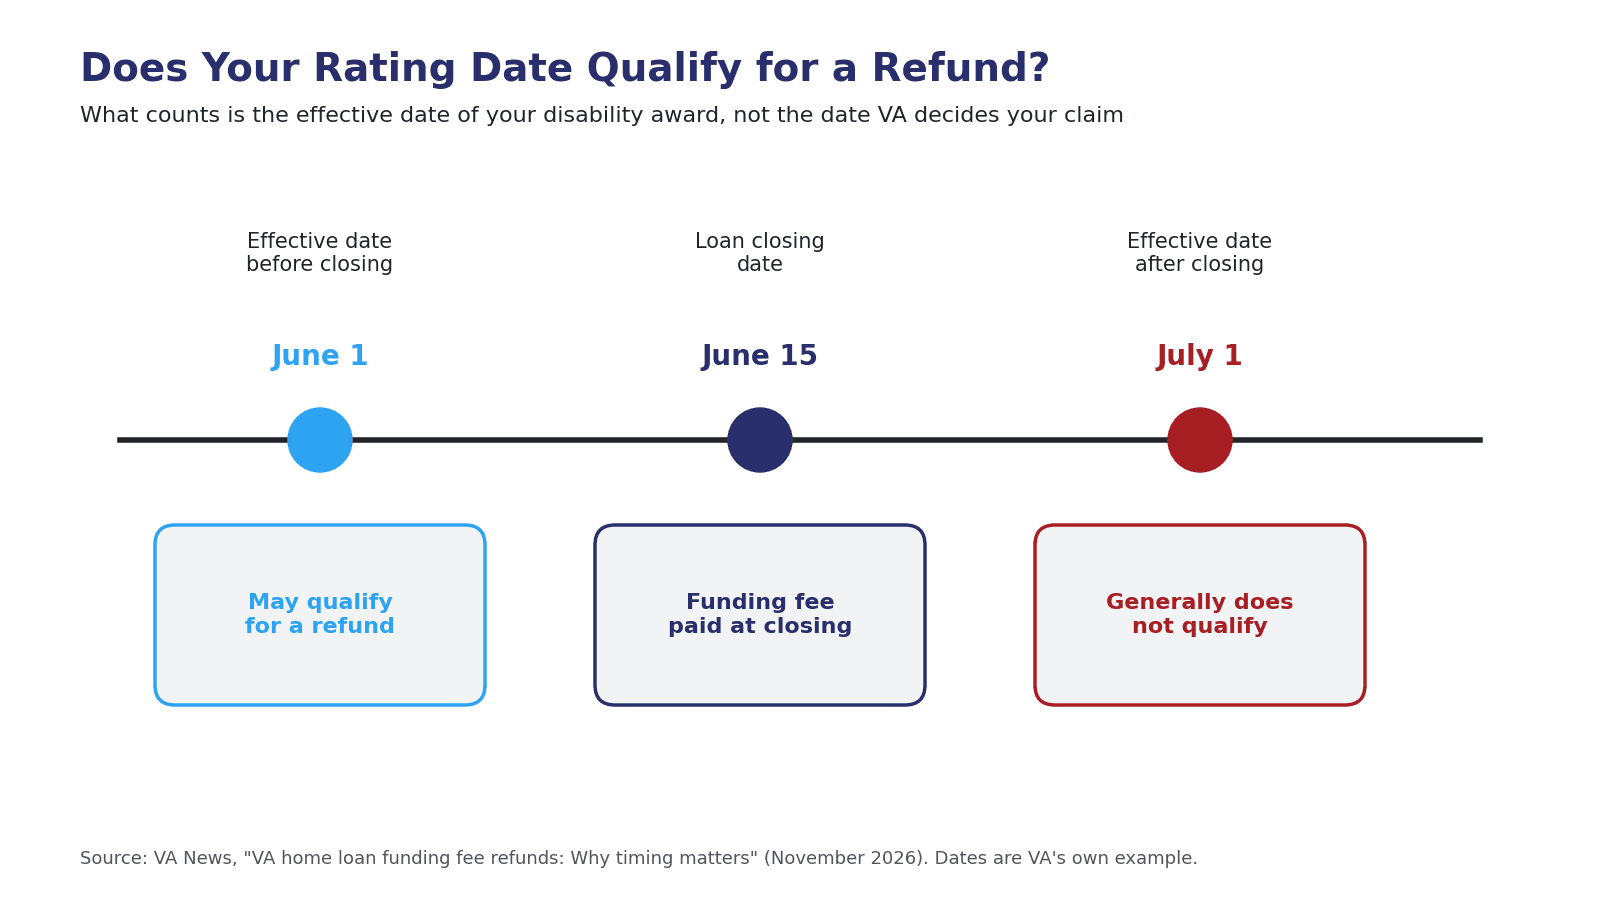 Only an effective date before your closing date can lead to a refund. Source: VA News, November 2026.
Planning Your Next Move?
Connect with Veteran & Military Spouse Real Estate Agents and VA Loan Experts You Can Trust.
There is one more catch. VA.gov says a proposed or memorandum rating issued after closing does not qualify you for a refund. You still pay the fee in that case.
How the Refund Gets Paid
Good news: in most cases you do not have to file anything. VA says refunds are automatic. It reviews rating decisions for effective dates that reach back before closing, then pays the money straight to the Veteran.
If you think you were charged the fee by mistake, there are two paths, per the VA article:
- Your lender can send a correction to VA.
- You can contact VA yourself to start the process.
The VA home loan line is 877-827-3702, Monday through Friday, 8:00 a.m. to 6:00 p.m. Eastern Time. VA.gov also says you can call your VA regional loan center about a refund.
Want a lender to look over your closing papers and your award letter? Talk with a VA-savvy lender through VeteranPCS. There is no cost and no obligation.
Watch Out for Refund Scams and Myths
The VA article warns about social media posts and videos that promise a refund just because you got a rating after you bought your home. As you now know, that is not how the rule works. Do not pay anyone to "unlock" a funding fee refund. If you qualify, VA pays it to you directly.
How to Avoid Paying the Fee in the First Place
The best refund is the one you never need. If you are getting out and plan to buy soon, timing your disability claim can help.
File before you separate. VA's Benefits Delivery at Discharge (BDD) program lets you file a disability claim 180 to 90 days before you leave active duty, per the VA pre-discharge claim page. You must be available for VA exams within 45 days of filing. A proposed or memorandum rating issued before closing can make you exempt.
Tell your lender early. If you have a claim pending, say so at the start. Your lender can check whether your COE shows an exemption and watch for an updated one before closing.
Free First-Time Homebuyer Guide
Make your move less stressful with our step-by-step first-time homebuyer guide.
We respect your privacy. Unsubscribe anytime.Show a Purple Heart if you have one. Active duty members who give proof of a Purple Heart on or before closing do not pay the fee.
If you already receive VA disability pay, it may also help you qualify. See our guide to using VA disability income to qualify for a mortgage. And for the rest of what you will pay at closing, read VA loan closing costs: what military buyers pay.
Frequently Asked Questions
Can I get my VA funding fee back if I get a disability rating after closing?
Only if the effective date of your award is before your loan closing date. A rating with an effective date after closing generally does not qualify.
Do I need to apply for a VA funding fee refund?
Usually not. VA says refunds are automatic when a rating decision has an effective date before closing. If you think you were missed, contact your lender or call VA at 877-827-3702.
Who is exempt from the VA funding fee?
Veterans who receive VA disability compensation, those eligible for it who get retirement or active-duty pay instead, surviving spouses on DIC, service members with a qualifying pre-discharge rating before closing, and active duty Purple Heart recipients.
Does a memorandum rating after closing qualify for a refund?
No. VA.gov says a proposed or memorandum rating issued after closing does not qualify you for a refund.
How much is the VA funding fee in 2026?
For a first-time purchase with less than 5% down, the fee is 2.15% of the loan amount. After first use, it is 3.3%. Putting 5% or 10% down lowers it to 1.5% or 1.25%.
Ready to buy with your VA loan? Connect with a VeteranPCS agent who knows your next duty station, or talk with a VA lender about your fee and your rating.
Know a Veteran who just got a rating after buying a home? Share this guide with your military network.
This content is for informational purposes. Consult a professional for personal financial decisions.