VA loan residual income requirements are one of the biggest reasons the VA loan has a strong track record. Most loans only look at your debt-to-income ratio. The VA also asks a simple, practical question: after you pay your mortgage, taxes and bills, is there enough money left for food, gas and everyday life? That leftover amount is your residual income. This guide shows the official VA chart, explains how lenders figure your number, and covers the special rule that helps active duty families near a base.
New to VA loans? Start with how a $0 down VA loan works and our VA loan eligibility guide.
What Is VA Residual Income?
Residual income is the money your household has left each month after paying:
- Taxes on your pay
- Your full house payment, including principal, interest, property taxes, homeowners insurance and any HOA (homeowners association) dues
- Estimated maintenance and utilities for the home
- Monthly debts, such as car loans, credit cards, student loans and child support
- Job-related costs, such as child care
The VA's loan analysis form calls this the "balance available for family support," per VA Form 26-6393. Federal rules in 38 CFR 36.4340 set the minimum amount you need, based on where you live, your family size and your loan amount.
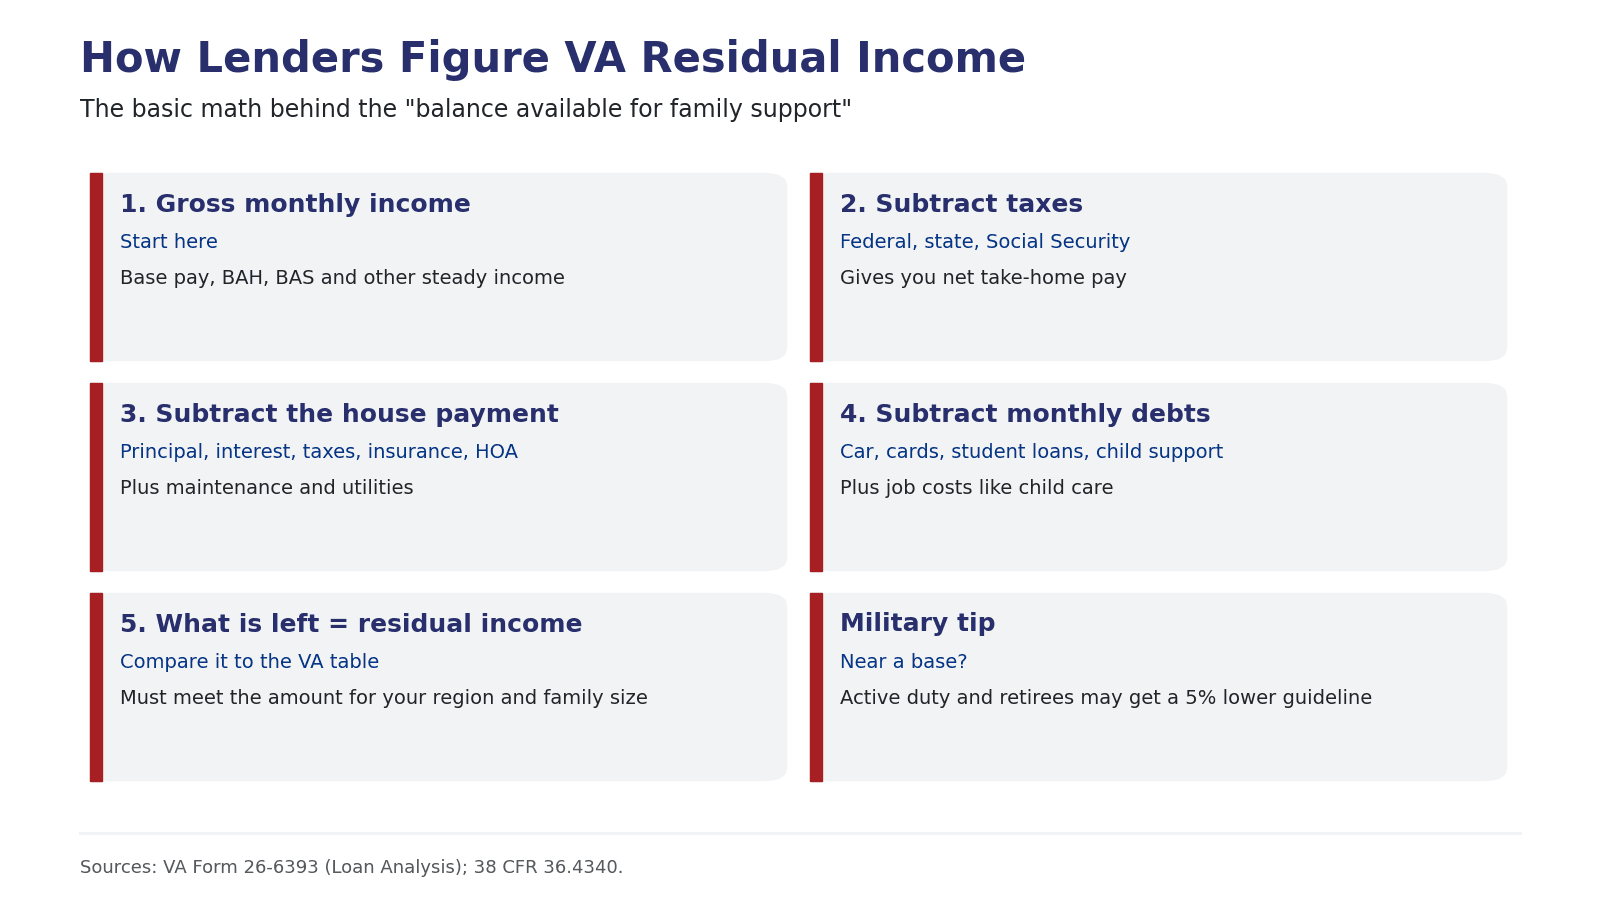 How lenders figure VA residual income. Sources: VA Form 26-6393; 38 CFR 36.4340.
The VA Residual Income Chart for 2026
The VA splits the country into four regions. Here are the states in each one, per 38 CFR 36.4340(e):
- Northeast: Connecticut, Maine, Massachusetts, New Hampshire, New Jersey, New York, Pennsylvania, Rhode Island, Vermont
- Midwest: Illinois, Indiana, Iowa, Kansas, Michigan, Minnesota, Missouri, Nebraska, North Dakota, Ohio, South Dakota, Wisconsin
- South: Alabama, Arkansas, Delaware, District of Columbia, Florida, Georgia, Kentucky, Louisiana, Maryland, Mississippi, North Carolina, Oklahoma, Puerto Rico, South Carolina, Tennessee, Texas, Virginia, West Virginia
- West: Alaska, Arizona, California, Colorado, Hawaii, Idaho, Montana, Nevada, New Mexico, Oregon, Utah, Washington, Wyoming
Loans of $80,000 and Above
Most home loans today fall in this group. Amounts are the minimum residual income needed each month.
| Family size | Northeast | Midwest | South | West |
|---|---|---|---|---|
| 1 | $450 | $441 | $441 | $491 |
| 2 | $755 | $738 | $738 | $823 |
| 3 | $909 | $889 | $889 | $990 |
| 4 | $1,025 | $1,003 | $1,003 | $1,117 |
| 5 | $1,062 | $1,039 | $1,039 | $1,158 |
For families of six or seven, add $80 for each extra person.
Loans of $79,999 and Below
| Family size | Northeast | Midwest | South | West |
|---|---|---|---|---|
| 1 | $390 | $382 | $382 | $425 |
| 2 | $654 | $641 | $641 | $713 |
| 3 | $788 | $772 | $772 | $859 |
| 4 | $888 | $868 | $868 | $967 |
| 5 | $921 | $902 | $902 | $1,004 |
For families of six or seven, add $75 for each extra person.
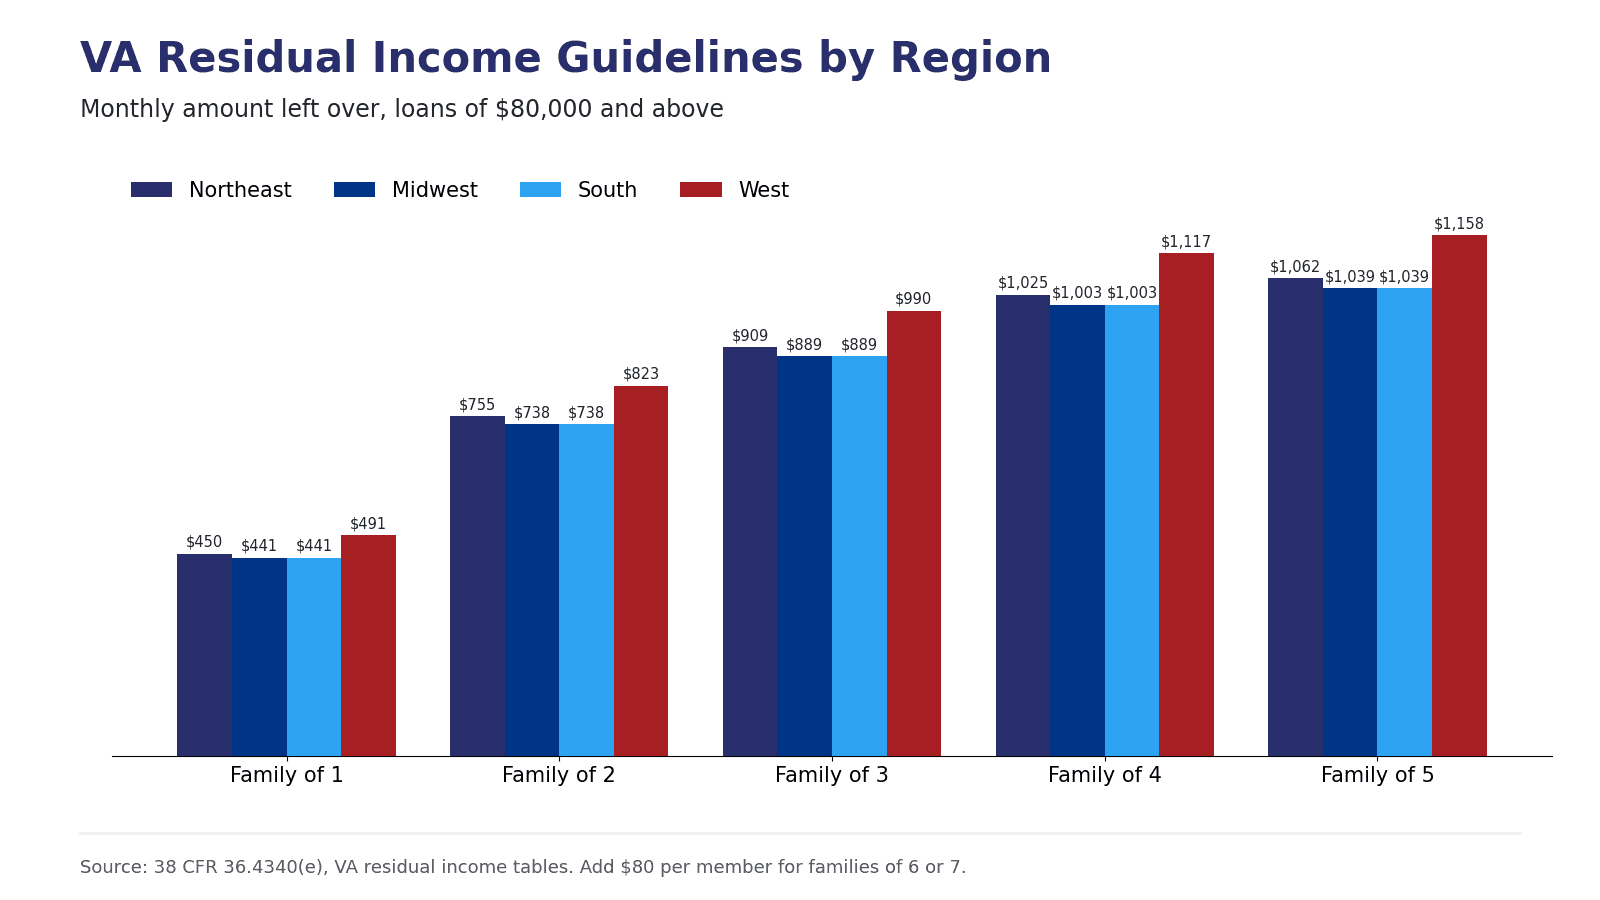 VA residual income guidelines for loans of $80,000 and above. Source: 38 CFR 36.4340(e).
These amounts have not changed since 1997. The VA raised them 4% that year, per the 1997 Federal Register notice, and the current rule still lists the same figures.
Who Counts in Your Family Size?
The rule says all members of the household must be counted, per 38 CFR 36.4340. That includes your spouse even if your spouse is not on the loan or the title. A spouse who is not on the loan can be left out only if they have stable, reliable income of their own that the lender can document.
Kids count, too. A family of four with two children uses the family-of-four row, even if only one parent is buying the home.
The 5% Military Rule
Here is a perk many military buyers never hear about. If you are on active duty or a military retiree, the lender can lower your residual income guideline by at least 5%. The catch: there must be clear signs you will keep using the services at a nearby military base, such as the commissary, exchange or medical clinic, per 38 CFR 36.4340(e).
Planning Your Next Move?
Connect with Veteran & Military Spouse Real Estate Agents and VA Loan Experts You Can Trust.
For example, a family of four in Texas on a loan of $80,000 or more needs $1,003 a month. With the 5% reduction, the target drops to about $953.
Want to know if you qualify for the reduction? Talk with a VA-savvy lender. There is no cost to connect.
How Residual Income Works With Your DTI Ratio
Your debt-to-income ratio (DTI) is your monthly debt payments divided by your gross monthly income, per the Consumer Financial Protection Bureau. For VA loans, the standard is 41% or less, per 38 CFR 36.4340.
Going over 41% does not always mean a no. If your residual income beats the guideline by at least 20%, the extra review the rule calls for is not required. Lenders often call this the "120% rule." This is why strong residual income can help a VA buyer whose DTI looks high on paper.
Some lenders add their own rules on top of the VA's. If one lender says no, another may say yes.
A Simple Example
The numbers below are made up to show the math. Your own figures will be different.
Say an active duty Soldier near a Texas base has a spouse and two kids, so the family size is four. The home is 1,800 square feet.
| Item | Monthly amount |
|---|---|
| Gross income (pay plus BAH and BAS) | $6,500 |
| Taxes withheld | -$700 |
| House payment (principal, interest, taxes, insurance) | -$2,300 |
| Maintenance and utilities (1,800 sq. ft. x $0.14) | -$252 |
| Car loan, credit card and student loan | -$700 |
| Child care | -$400 |
| Residual income | $2,148 |
The South guideline for a family of four is $1,003, or about $953 with the military reduction. This family clears it easily.
Now look at DTI. The house payment plus debts is $3,000, which is about 46% of $6,500. That is over 41%. But residual income of $2,148 is more than 120% of the guideline, so this file has a strong case.
The $0.14 per square foot figure for maintenance and utilities comes from the VA's credit standards job aid. Your lender may use local utility costs instead.
BAH (Basic Allowance for Housing) and BAS (Basic Allowance for Subsistence) are tax-free, and lenders can count them as income. To see how much house your BAH supports, read how much house can you afford on BAH.
Free First-Time Homebuyer Guide
Make your move less stressful with our step-by-step first-time homebuyer guide.
We respect your privacy. Unsubscribe anytime.How to Improve Your Residual Income
If your number comes up short, you have options:
- Pay down a debt. Paying off a car loan or credit card frees up money every month.
- Pick a lower price. A smaller loan means a smaller house payment.
- Look at a smaller or more efficient home. Fewer square feet lowers the maintenance and utility estimate.
- Add a co-borrower. A spouse or another eligible borrower can add income. See our guide to VA joint loans.
- Count all your income. VA disability pay can count. Read using VA disability income to qualify for a mortgage.
- Ask about seller help. Seller-paid closing costs do not change your monthly budget, but they keep cash in the bank. See VA loan closing costs.
Your credit matters, too. See our guide to VA loan credit score requirements.
Frequently Asked Questions
Is residual income required for every VA loan?
Lenders use the VA's credit standards, including residual income, when they underwrite a VA purchase loan. The rules can work differently for refinances, so ask your lender how they apply to yours.
Does the VA residual income chart change every year?
No. The amounts in the current rule match the 1997 figures. Your BAH and pay change, but the chart has not.
Is Hawaii or Alaska in a special region?
No. Both are in the West region, which has the highest guideline amounts.
Can I get a VA loan with a DTI over 41%?
Yes, it is possible. Strong residual income, at least 20% above the guideline, is the most common reason a lender approves a higher DTI.
Get Help Running Your Numbers
Residual income can sound complicated, but a good VA lender can run it in minutes. Connect with a VA-savvy lender to check your numbers, then find a military-friendly agent near your next base.
Know someone getting ready to buy with a VA loan? Share this guide with your military network.
This post was researched by VeteranPCS using VA, federal rule and CFPB sources.
This content is for informational purposes. Consult a professional for personal financial decisions.